
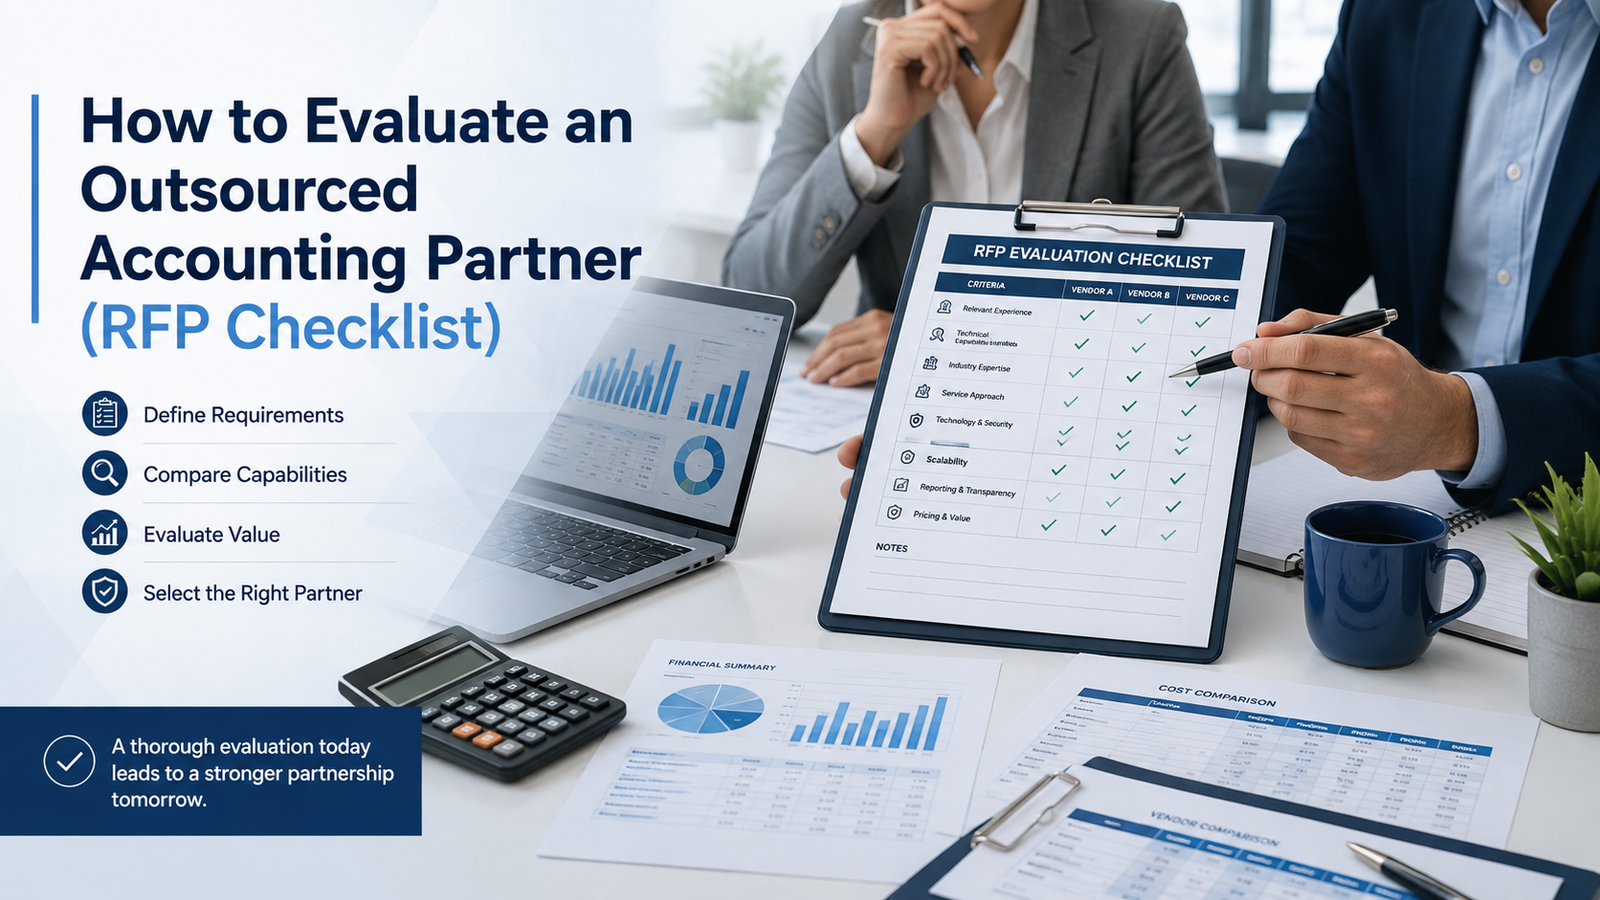
Evaluating an outsourced accounting partner usually comes down to one question buried under a dozen smaller ones: can this firm actually run our books the way we need them run, or will we be back in the market in 18 months? Most RFPs never get close to answering it. They ask about years in business, client counts, and software platforms, and they get back answers that all sound roughly the same, because those are the easy questions to prepare for.
Skip ahead if that’s all you need. Stay for the fuller version if you want a checklist built to actually separate a strong fit from a polished pitch.
TL;DR
- The accounting talent shortage is structural, not cyclical, so a provider’s ability to actually staff your engagement matters as much as their pitch.
- A mismatched provider doesn’t just cost money to fix. It costs a missed close, a restated number, or a board question you can’t answer, plus months of restarted onboarding with a new firm.
- Match the outsourcing model to your needs first: full function, staff augmentation, or project-based work. An RFP built for the wrong model wastes everyone’s time.
- Score the 10 checklist categories below (scope, staffing, technology, security, SLAs, onboarding, pricing, references, continuity, and communication) before you take a single sales call.
- Vague answers on staffing, pricing, or references are the clearest sign a provider is describing a concept rather than a real process.
You’ve probably run a vendor RFP before, and it likely worked well enough. Outsourced accounting is a different kind of decision. The vendor is not delivering a product you can inspect before you buy it. They’re taking over a function: your board, your bank, and your auditors all depend on being right every single month.
That difference is why a generic RFP template fails here more often than it succeeds. A firm can look identical to 3 competitors on paper and still be the wrong fit once your close process, your ERP, or your audit timeline enters the picture. This piece breaks down what actually belongs in an RFP checklist for an outsourced accounting partner, why most companies skip the questions that matter most, and what a vague answer is telling you before you sign anything. If you’re still weighing whether outsourcing makes sense at all, our breakdown of the core benefits is a useful starting point before you build an RFP around it.
What this covers
- Why the accounting talent shortage has changed what “good enough” outsourcing looks like
- What a bad-fit accounting partner actually costs you mid-engagement, not just at signing
- A full RFP checklist broken into the 10 categories that separate a real partner from a vendor that’s guessing
- What a vague RFP answer tells you, category by category
Why evaluating an outsourced accounting partner matters more than it used to
Outsourcing finance and accounting work is not a fringe move anymore. It’s become a standing part of how finance leaders staff their function, and the data backs that up.
- 80% of executives plan to maintain or increase their investment in third-party outsourcing. Source: Deloitte Global Outsourcing Survey, via Prialto
- Roughly 1 in 4 CPA firms already outsource at least part of their accounting or bookkeeping work to an outside provider. Source: Acobloom
- 65% of executives cite the ability to focus internal teams on core work, and 63% cite cost, as the top reasons for outsourcing. Source: Deloitte Global Outsourcing Survey, via Prialto
That growth changes the shape of the market you’re buying into. A decade ago, an outsourced accounting evaluation was mostly a cost conversation: could a provider do the work for less than an in-house hire. The calculation now includes a second variable that didn’t carry nearly as much weight before, which is whether qualified accounting talent is available to staff your engagement at all.
Both of Deloitte’s top-cited reasons for outsourcing assume the provider can actually deliver consistent execution. That assumption is exactly what an RFP is supposed to test, and it’s exactly what most RFPs fail to test with any rigor.
Why the accounting talent shortage changes the buyer’s risk
The accounting profession is short on people, and the shortage is not a cyclical dip. It’s structural, and it directly affects whether the firm sitting across the table from you in an RFP process can actually staff what they’re proposing.
- 83% of financial leaders say they can’t find qualified accounting talent, up from 70% two years earlier. Source: CFO Pulse Survey 2024, via AACSB
- CPA exam participation has declined by more than 30% since 2016, and the drop has been sustained rather than a single bad year. Source: Talentfoot
- The Bureau of Labor Statistics projects roughly 124,000 accounting and auditing job openings every year, a number the shrinking pipeline cannot fill on its own. Source: BLS Occupational Outlook Handbook, via Ramp
- Accounting program enrollment climbed to 266,506 students in the spring 2025 semester, a 12.4% jump from the year before and the highest total since 2020, a genuine bright spot worth naming honestly. Jan Taylor, the AICPA’s academic-in-residence, said the trend is encouraging because the rate of decline has slowed year over year, a sign that recent recruiting initiatives are starting to take hold. Source: Journal of Accountancy
- Finance roles requiring a CPA credential now take an average of 73 days to fill, 41% longer than comparable roles that don’t require the license. Source: Talentfoot
- Accounting firms themselves report a stronger hiring outlook than in recent years, according to the AICPA’s own trends reporting, even as the underlying pipeline contraction continues. Source: AICPA & CIMA
That recovery in enrollment is real, but it’s early, and it takes years for a new accounting student to become a licensed, engagement-ready CPA. Research on the pipeline also shows the shortage isn’t distributed evenly across the profession, with the decline concentrated more heavily in public accounting and tax than in audit. In the meantime, the shortage is showing up directly in hiring timelines, which is why it matters for an RFP specifically. A staffing gap that slows down your own internal hiring slows down your outsourced provider’s hiring too. If a firm can’t tell you how it sources and retains accounting talent in this exact labor market, it’s proposing a staffing model it may not be able to deliver once your engagement actually starts.
What a bad-fit accounting partner costs you mid-engagement
The failure rate for outsourcing relationships in general is not a small number. Industry estimates put it between 40% and 70%, a range wide enough to reflect how much the outcome depends on how the relationship was structured going in, not just who was picked.
| Where the cost shows up | What it actually looks like |
| Functional damage | A missed close, a restated balance, or a bank covenant question you can’t answer on the call where it’s asked. Unlike a marketing vendor or an IT help desk, accounting touches nearly every other part of the business, so the damage doesn’t stay contained to the accounting team |
| Root causes | Vendors that overpromise during the sales process, contracts that don’t align the provider’s incentives with the client’s goals, and clients that sign and then stop actively managing the relationship. None of these are visible in a polished RFP response, which is exactly why the RFP has to be built to surface them before you sign. MetricNet’s research on outsourcing turnover and The Office Gurus’ work on outsourcing governance both point to the same root pattern: weak governance after signature, not a bad initial pick, is usually what turns a promising engagement into a failed one. |
| Switching costs | Lost institutional knowledge of your chart of accounts, intercompany eliminations, and the judgment calls that don’t live in a policy document. Onboarding restarts from zero, usually during a quarter where a transition is the last thing you need |
| Internal trust | Once a finance team has been burned by a provider that didn’t deliver, the next proposal gets a harder internal audience, even if that provider is a genuinely better fit |
A rigorous RFP process up front protects you from all 4 of these outcomes. It also protects the eventual provider, since a well-scoped RFP sets expectations both sides can actually meet instead of expectations that sound good in a sales deck. It’s the same logic covered in our piece on the hidden costs of a rushed hiring decision: the sticker price of a bad fit is rarely the real price.
When to outsource full function vs staff augmentation vs project work
Not every accounting need calls for the same outsourcing model, and an RFP written for the wrong model wastes everyone’s time before the first proposal is even due. Our guide to matching the staffing solution to your needs covers this decision in more depth than this section will.
Full-function outsourcing makes sense when you need an entire process end to end, close, reporting, accounts payable, accounts receivable, managed by a provider with its own review layers and quality control. It fits companies without an internal controller or finance lead who can own the function directly.
Staff augmentation makes sense when you have internal leadership and process already in place, but you need dedicated hands to execute it, whether that’s a bookkeeper, an AP specialist, or a senior accountant embedded in your existing team. You keep control of the process. The provider supplies the person.
Project-based support makes sense for a defined, time-boxed need: an audit prep sprint, a system migration, a catch-up bookkeeping project, or coverage during a parental leave or open req. It’s the right call when the need has a clear end date and doesn’t justify a standing engagement.
Most companies actually need a blend, and a provider worth evaluating should be able to say so plainly instead of steering every conversation toward whichever model they sell hardest. If a firm can only describe one delivery model regardless of what you ask them, that’s worth noting before you get further into the process.
The RFP checklist: what to ask before you sign
This is the part most RFP templates get wrong. They ask broad questions that invite broad answers. The categories below are built to force specifics, because specifics are what separate a provider that’s actually done this work from one that’s describing what the work should theoretically look like.
Scope of service and delivery model
Scope disputes are one of the most common sources of friction once an engagement starts, usually because the RFP described the work in broad strokes and both sides filled in the gaps differently. Getting the delivery model in writing early prevents a lot of that friction later.
- Which specific functions are in scope: AP, AR, general ledger, reconciliations, financial reporting, payroll, tax support, or some combination?
- Is the delivery model full outsourcing, staff augmentation, or a hybrid, and can the provider flex between them as your needs change?
- Who owns final review and sign-off on financials: the provider, your internal team, or a shared process?
- What’s explicitly out of scope, and how does the provider handle work that falls outside the original scope once the engagement starts?
Staffing, credentials, and bench depth
This is the category where a vague answer tells you the most, and it’s also the category most RFPs probe the least. The people doing the work day to day matter more to your outcome than the firm’s overall size or reputation.
- Who specifically will work on your account, by name and role, not just by job title category?
- What are the credentials and experience level of the people actually doing the work, versus the people who ran the sales process?
- What happens if your dedicated accountant leaves the firm or gets pulled onto another account? Is there a documented backup and knowledge-transfer process?
- How does the provider source and vet accounting talent given the current hiring market, and how long does it typically take them to staff a role like yours?
Technology stack and integrations
A provider that has never worked in your specific ERP is starting your engagement with a learning curve you’re paying for. Confirming direct platform experience up front avoids finding this out during your first close. Platform fit matters enough that it’s worth checking a provider’s track record on your specific system, whether that’s NetSuite or Workday, rather than assuming general accounting experience transfers.
- Which accounting platforms and ERPs does the provider actively support, and have they run an engagement on your specific system before?
- How does the provider handle system access: dedicated logins, shared environments, or a proprietary portal, and what does that mean for your audit trail?
- What tools does the provider use for workflow tracking, document management, and client communication, and can you see them before signing?
- If the provider uses automation or AI-assisted tools for parts of the process, where exactly are those tools used, and where does a human still review the output? Deloitte’s Global Business Services Survey found finance among the top functions where generative AI tools are already being layered into workflows, so this is not a hypothetical question. A provider’s overall market position on outsourced finance delivery, as tracked in independent research like the ISG Provider Lens for finance and accounting outsourcing, can be a useful cross-check against what they claim in their proposal.
Data security, controls, and compliance
Your financial data is one of the most sensitive assets in the company, and an outsourced provider needs access to a lot of it to do the job. This category is not a box-checking exercise. It’s the section your auditors will ask about directly. If you’re not familiar with what a SOC 2 report actually covers, the AICPA’s Trust Services Criteria are worth a quick read before your first vendor call.
- What certifications does the provider hold: SOC 1, SOC 2, or industry-specific equivalents, and can they provide the actual audit report, not just a logo on their website?
- How is client financial data segregated between accounts, and who inside the provider’s organization has access to yours?
- What’s the provider’s process for background checks and ongoing screening of staff who will have access to your financial systems?
- If your industry has specific compliance requirements, healthcare, financial services, government contracting, does the provider have direct experience meeting them?
Service levels and performance metrics
A close date promised verbally during a sales call means nothing once the engagement is live. Get commitments in writing, with a stated consequence if they’re missed, or don’t count on them at all.
- What specific service level agreements does the provider commit to in writing: close timelines, reconciliation turnaround, response time on questions?
- What happens contractually if the provider misses an SLA? Is there a remedy, or is it just a conversation?
- What metrics does the provider track and report on their own performance, and how often do they share that reporting with you?
- Does the provider offer a trial period or a defined ramp-up phase before full SLAs kick in, and what does success look like at the end of it?
Transition and onboarding process
The first 60 to 90 days set the tone for the entire relationship. A provider without a documented onboarding plan is asking you to trust that things will come together, instead of showing you how.
- What does the provider’s onboarding process actually look like, week by week, from contract signature to first live close?
- How does the provider handle the handoff from your current process, whether that’s an internal team or a previous vendor?
- Who’s responsible for documenting your existing policies and procedures, and does the provider build that documentation or expect you to hand it over?
- What’s the provider’s track record on onboarding timelines actually matching what they proposed?
Pricing structure and contract terms
The proposed rate is rarely the number that matters most. The number that matters is what you actually pay once volume shifts, scope creeps, or an audit request lands mid-quarter.
- Is pricing fixed fee, hourly, or a hybrid, and does it change based on transaction volume or scope?
- What’s included in the base price versus billed separately: software licensing, month-end adjustments, ad hoc reporting requests, audit support?
- What’s the contract term, and what does the exit clause actually require if the relationship doesn’t work out?
- Are there price increases built into the contract, and if so, how are they triggered and capped?
References, tenure, and track record
A reference list curated by the provider will always lean positive. The value is in what you ask for those references, not just in who’s on the list.
- Can the provider give you references from clients in your industry and at your revenue size, not just their strongest logo overall?
- How long has the provider’s average client relationship lasted, and can they explain their client retention rate with a real number, not a vague assurance?
- Ask directly why past clients left. A provider confident in its process will have a real answer. One without a process will change the subject.
- Has the provider ever been terminated for cause, and if so, what happened?
Business continuity and scalability
An accounting partner that fits your business today can become the wrong fit in 18 months if growth outpaces their staffing model. Test for that scenario before you sign, not after you hit it.
- What’s the provider’s plan if your business grows 3 times over the next 2 years? Can their staffing model scale with you, or does growth require a full re-negotiation?
- What’s the provider’s disaster recovery plan for their own systems, and how does that plan protect your financial data specifically?
- If the provider has a delivery center outside the US, how does that affect data residency, time zone coverage, and your ability to reach someone during your own business hours?
- What happens to continuity if the provider itself gets acquired or restructured mid-contract?
Communication and governance cadence
The best outsourced accounting relationships run on a rhythm both sides can predict. Ask the provider to describe that rhythm concretely, not just confirm that “communication is a priority.”
- What’s the standard meeting cadence: weekly check-ins, monthly business reviews, quarterly strategy sessions?
- Who is your single point of contact, and what’s the escalation path if that person is unresponsive or the relationship needs a harder conversation?
- How does the provider handle disagreements over a judgment call, a classification question, or a reporting interpretation?
- Does the provider proactively flag issues before they become problems, or only respond once you’ve raised them?
How to structure the RFP process itself
The checklist above is only as useful as the process wrapped around it. A few structural choices make the difference between an RFP that surfaces real signals and one that just collects polished proposals.
- Involve the people who will actually work with the provider, not just procurement. Your controller or finance lead will ask sharper technical questions than a generalist buyer, and they’re the ones who will live with the outcome. Leaving them out of the evaluation is a common reason the wrong provider gets selected on price and presentation alone.
- Score responses against the checklist categories before you take a single sales call. It’s easy for a strong presenter to talk you past a weak written answer if you meet the people before you’ve read what they actually committed to on paper. Reading first, then meeting, keeps the evaluation anchored to substance.
- Send the same RFP to at least 3 providers, even if you already have a frontrunner. A single-bidder process weakens your position on pricing and contract terms, and it removes your ability to tell whether an answer is genuinely strong or just the only answer you’ve seen.
- Build in time for a follow-up round of questions after initial proposals come back. The first round of answers tells you who took the RFP seriously. The follow-up round, where you push on the vague spots from round one, tells you who has a real process behind the polish.
- Put a defined decision deadline on the process itself. An open-ended RFP timeline invites scope creep on your side and stalling on the provider’s side. A clear date keeps everyone, including your own internal stakeholders, moving toward an actual decision instead of an indefinite comparison.
Red flags in an RFP response
A strong RFP process is as much about reading what’s missing as it is about reading what’s there. A few patterns are worth watching for directly.
| Red flag | What it looks like | Why it matters |
| Vague staffing answers | The team is described as “a dedicated squad of experts” with no named credentials, tenure, or point of contact | They’re selling a concept, not a staffing plan |
| Pricing that avoids specifics | The provider won’t lay out what’s included and what triggers an extra charge until after signature | Sets up a dispute you don’t want during your first month-end close |
| References that all sound identical | Every reference describes the same glowing experience, with no mention of a challenge or adjustment period | Suggests a curated list rather than an honest sample. Ask for one more name yourself |
| Answers that stop at the question asked | The response covers exactly what’s on the page and nothing more | A provider who’s done this work before usually flags something you didn’t think to ask. One reciting a template won’t |
VALiNTRY’s approach to outsourced accounting staffing
VALiNTRY staffs finance and accounting functions for companies across accounting staff augmentation, accounts payable, accounts receivable, bookkeeping, and platform-specific roles on systems like NetSuite, Workday, and Sage. We back that work with an 86% candidate retention rate across our staffing verticals, a number we’ll walk through in detail if it’s part of your evaluation. Our case for why outsourced accounting staffing fits most organizations covers the broader reasoning behind this piece.
The accounting talent shortage covered earlier in this piece isn’t a reason to lower your bar in an RFP. It’s the reason the bar matters more than it used to. A tight labor market rewards the companies that ask sharper questions during evaluation, not the ones that pick the fastest-sounding proposal and hope the staffing holds up.
Run any provider you’re evaluating, including us, through the checklist above. Get in touch about your finance and accounting staffing needs if you want a second opinion on how a proposal stacks up, or if you’d like a direct answer to any of the questions in this checklist before you send out your RFP.
FAQ
What should be included in an RFP for outsourced accounting services?
An RFP for outsourced accounting services should cover scope of work, staffing and credentials, technology and system compatibility, data security certifications, service level commitments, onboarding timeline, pricing structure, references, business continuity plans, and communication cadence. Skipping any one of these categories leaves a gap a vendor’s sales team is likely to fill with a vague answer.
How long should an outsourced accounting RFP process take?
Most RFP processes for outsourced accounting run 4 to 8 weeks from sending the RFP to signing a contract, depending on how many providers you’re evaluating and how thorough your reference checks are. Rushing this timeline is one of the more common reasons a mismatch doesn’t surface until after the engagement starts.
What’s the difference between full outsourcing and staff augmentation for accounting?
Full outsourcing hands an entire process, such as the full close cycle or accounts payable end to end, to the provider, with the provider’s own management and quality control layered on top. Staff augmentation places a dedicated accounting professional inside your existing team and process, with you retaining ownership of how the work gets done. The right choice depends on whether you already have internal leadership to direct the function.
Why is the accounting talent shortage relevant to choosing an outsourcing partner?
A provider’s ability to deliver depends on their ability to staff qualified accountants, and that talent pool has gotten tighter. CPA exam participation has declined by more than 30% since 2016, and 83% of financial leaders report difficulty finding qualified accounting talent. A provider that can’t explain how they source and retain talent in this market may struggle to staff your engagement consistently once it’s live.
What certifications should an outsourced accounting provider have?
Look for SOC 1 or SOC 2 certification at minimum, since these directly address financial data handling and internal controls. Ask to see the actual audit report rather than taking a certification claim at face value. If your industry carries additional compliance requirements, confirm the provider has direct experience meeting them, not just general familiarity.
How do you check references for an outsourced accounting firm?
Ask for references from clients in your industry and at a comparable revenue size, not just the provider’s strongest overall logo. Ask reference clients directly what went wrong at any point in the relationship, not just what went right. A provider confident in their process will not hesitate to connect you with a client who can speak honestly, including about a rough patch that got resolved.
What pricing model is most common for outsourced accounting services?
Fixed-fee pricing and hourly pricing are both common, with fixed-fee more typical for full-function outsourcing and hourly more typical for staff augmentation and project work. Whatever the structure, confirm in writing what’s included in the base price and what triggers an additional charge, since this is one of the more common sources of disputes once an engagement is underway.
Can an outsourced accounting engagement scale as a company grows?
It can, but not automatically. Ask directly how a provider’s staffing model handles a significant jump in transaction volume or headcount, and whether that growth requires a contract renegotiation or fits within the existing agreement. A provider without a clear answer here is planning for your current size, not your next 2 years.
What happens if an outsourced accounting relationship doesn’t work out?
Review the exit clause in the contract before you sign, not after you need it. A well-structured contract spells out notice periods, data handoff requirements, and transition support obligations if either party ends the relationship. Given that industry failure rates for outsourcing relationships run as high as 40% to 70%, treating the exit clause as a formality is a mistake worth avoiding upfront.
Should a company use one outsourced accounting provider or split functions across several?
Both approaches work, and the right one depends on complexity. A single provider handling multiple functions, AP, AR, and general ledger together, simplifies coordination and gives one team full visibility into how the pieces connect. Splitting functions across specialized providers can make sense for a company with a highly specific need in one area, but it adds a coordination burden that a single-provider model avoids.
How many providers should be included in an outsourced accounting RFP?
Sending the RFP to at least 3 providers is a reasonable baseline for most companies. It gives you a real basis for comparing pricing, scope, and staffing approach, and it keeps a single vendor from becoming a default choice simply because no one else was in the running. Fewer than that, and it becomes difficult to tell a strong answer from a merely available one.
Who inside the company should be involved in evaluating an outsourced accounting partner?
At minimum, involve whoever will manage the day-to-day relationship once the contract is signed, typically a controller, CFO, or finance director, alongside whoever owns procurement or vendor risk. Leaving the technical evaluation entirely to a generalist buyer is one of the more common reasons a provider gets chosen on price and presentation rather than genuine fit.
A tight accounting labor market does not excuse a rushed evaluation. The checklist has to do the work a sales pitch will not.